
All blogs
19.11.2026
Real View
Media
Croatia’s high VAT on new-build properties is doing double damage - Ivan Kovačić for Forbes Croatia
Croatia applies one of the highest VAT rates on new-build properties in the European Union, at 25%. This tax policy makes housing less affordable for domestic buyers while reducing the competitiveness of second homes along the Adriatic coast. It also raises the question of whether lower taxation could encourage investment and increase housing supply.
Speaking to Forbes Croatia, Ivan Kovačić, managing director of Remington Real Estate, the exclusive affiliate of Christie’s International Real Estate in Croatia, examines the impact of VAT on the Croatian property market. His analysis compares taxation across European countries and highlights the need for a more strategic approach to housing supply, investment and international competitiveness.
How does high VAT affect Croatia’s property market?
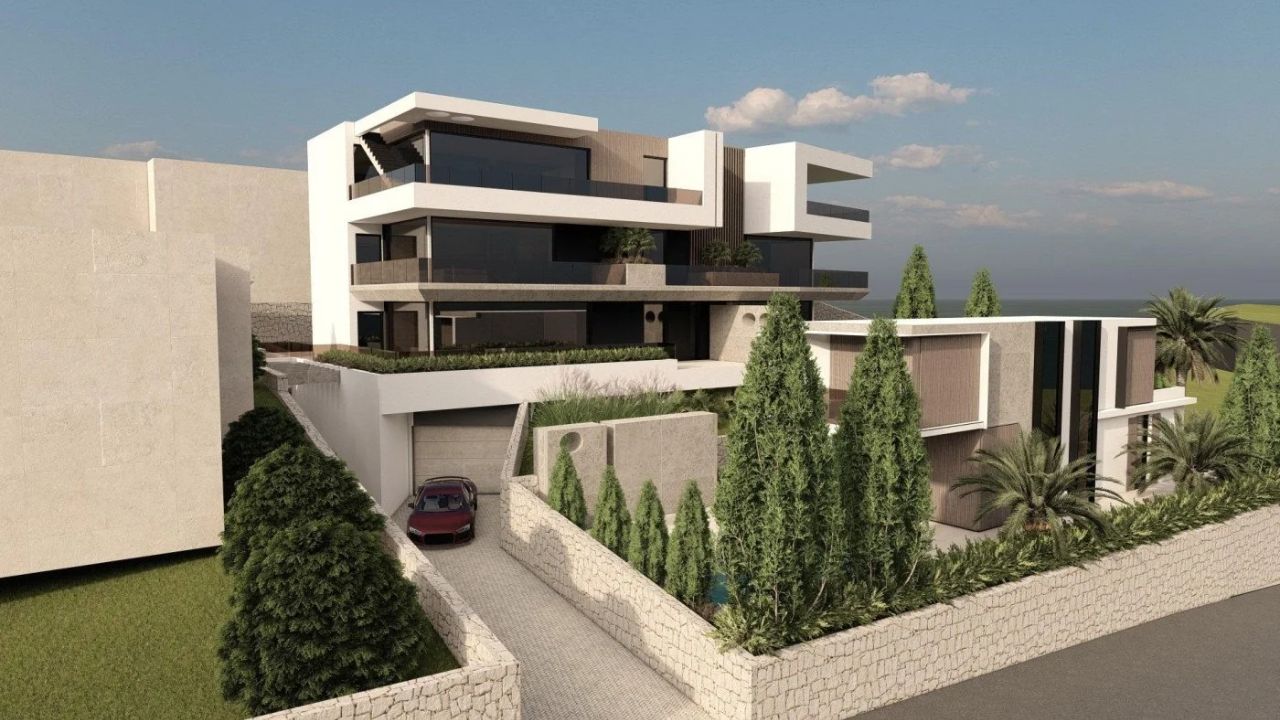
Contemporary residential development with sea views and private outdoor spaces - Opatija Riviera
Croatia’s 25% VAT rate places a significant tax burden on buyers of newly built properties. Its impact is particularly evident in two areas: housing affordability for Croatian residents and the competitiveness of second homes on the Adriatic coast.
For domestic buyers, higher taxation adds to the cost of purchasing a permanent home. At the same time, it makes new developments along the Adriatic less competitive compared with properties in other Mediterranean destinations.
Kovačić points out that Croatia’s property market does not operate in isolation. It forms part of a wider European and international market in which countries compete to attract buyers and investment.
Businesses regularly analyse their competitors, prices and operating conditions to remain competitive. Kovačić argues that governments should take a similar approach when developing economic policies.
Although the Croatian government has introduced a measure allowing eligible first-time homebuyers to reclaim 50% of the VAT paid, this alone does not address the wider challenges facing the market.
How does VAT on new-build properties compare across Europe?
European countries take significantly different approaches to taxing newly built residential properties.
These differences also raise the question of whether Croatia missed earlier opportunities to introduce more favourable taxation and how much flexibility it now has under European regulations.
Germany provides an interesting comparison. Under its tax system, VAT at 19% is charged on construction costs rather than the final sale price of a newly built property. Buyers instead pay real estate transfer tax ranging from 3.5% to 6.5%, depending on the federal state.
Kovačić illustrates the difference using an apartment with construction costs of €2,500 per square metre, land costs of €1,000 per square metre and a final sale price of €6,000 per square metre.
In this example, VAT in Croatia amounts to €1,200 per square metre. In Germany, VAT on construction costs amounts to €475. Even after including German real estate transfer tax, the overall tax burden remains approximately 28% to 43% lower than in Croatia.
Other European countries also apply considerably lower rates.
Spain and Italy generally apply 10% VAT to new-build properties, while Italy offers a reduced rate of 4% to eligible first-time buyers.
Hungary has the highest standard VAT rate in the European Union, at 27%, yet applies a reduced rate of 5% to a significant proportion of new residential developments. Poland applies an 8% rate to a substantial part of its residential property market.
In the United Kingdom, the first sale of qualifying newly built homes is zero-rated for VAT, although a separate progressive property transaction tax applies.
These comparisons must be considered within the broader tax system of each country. Nevertheless, they illustrate the different approaches European governments take towards residential property taxation.
Mediterranean countries offer a different approach
Cyprus, Malta and Portugal are particularly relevant examples, as all three countries compete within the Mediterranean property market and attract international buyers.
Cyprus applies a reduced VAT rate of 5% to certain properties intended as permanent residences. Malta generally does not charge VAT on property sales, while property transactions in Portugal are largely exempt from VAT.
From 2026, Portugal also applies a reduced VAT rate of 6% to the construction of certain residential properties.
These examples demonstrate that taxation can serve a broader economic purpose beyond generating government revenue. It can also influence investment decisions and the competitiveness of a country’s property market.
For Croatia, this is particularly important along the Adriatic coast, where international buyers can compare properties, prices and investment conditions across several Mediterranean destinations.
Could lower VAT increase housing supply?
One of the main challenges facing Croatia’s property market is the shortage of available housing, particularly in the affordable segment.
Kovačić argues that this problem cannot be resolved solely through buyer subsidies and measures designed to stimulate demand.
At the same time, rising construction, land and financing costs are putting increasing pressure on the profitability of new developments. Along the Adriatic coast, these challenges are compounded by high prices, urban planning restrictions and growing competition from other Mediterranean destinations.
Reducing VAT could improve the financial viability of new projects, encourage additional investment and ultimately increase housing supply.
However, lower taxation would not necessarily result in an equivalent reduction in property prices.
“We cannot say with certainty whether a tax reduction would translate into lower selling prices or whether part of the benefit would end up in developers’ pockets,” Kovačić explains.
Even if developers retained part of the tax savings, a greater number of completed projects could increase competition and place pressure on prices over time.
The potential benefits of lower VAT should therefore be assessed not only in terms of immediate price reductions but also through their longer-term impact on investment and housing supply.
Falling transaction volumes highlight growing market challenges
Recent figures presented in the analysis indicate a substantial slowdown in Croatia’s residential property market.
The number of residential property sales fell by 42% in the first quarter of 2026 and by 33% in the second quarter, compared with the corresponding periods in 2025.
At the same time, property purchases by foreign nationals declined by more than 20% during 2025.
Despite fewer transactions, property prices continue to rise at double-digit annual rates, making it increasingly difficult for Croatian residents to afford a home.
Kovačić also points to more than €40 billion held in household deposits in Croatian banks. He argues that the government has not created sufficient conditions to direct more of this capital towards productive investment, including residential development.
These trends raise questions about the sustainability of the market and whether existing measures are addressing its underlying challenges.
Why Croatia needs a more proactive property market strategy
According to Kovačić, the current challenges are not simply the result of recent economic developments. They also reflect years of delayed decisions and policies that have not adequately addressed the needs of the property market.
Rather than anticipating market developments and introducing timely measures, Croatia has too often responded only after problems have become apparent.
Taxation, urban planning and investment conditions are closely connected. Together, they influence housing affordability, the feasibility of new developments and Croatia’s competitiveness as a destination for property investment.
Kovačić therefore calls for a more systematic approach to policymaking, with greater involvement from qualified professionals and less political influence over technical decisions.
The experience of other European countries shows that different approaches to property taxation are possible. However, their effectiveness must be assessed within the wider economic and regulatory environment.
Croatia’s 25% VAT rate is therefore more than a question of the immediate cost to buyers. It also affects investment decisions, the development of new housing and the country’s long-term position in the international property market.
Kovačić concludes that countries, regions and cities compete for investment and economic opportunities in much the same way as businesses.
“Croatia can no longer afford to make that competition even more difficult through its own tax policies.”
Read the full article: Forbes Croatia.
November 19, 2026
Share
Related posts

Real View
Media
Croatia's new real estate brokerage law: what it actually changes, and what it doesn't - Ivan Kovačić for Forbes Croatia

Media
From Tina Turner to Christie's International Real Estate: Ivona Brnelić's journey
Real View
Media